Seemingly unconnected headlines over the past week should give India's economy watchers fresh room for concern. Inflation, like Alladin's genie, is difficult to put back into the bottle — and it doesn't help when the government goes about it with the assumption that most of the answers to the problem lie at the Ballard Estate in Mumbai, the headquarters of the Reserve Bank of India(RBI), and not the North Block, where the finance minister sits.
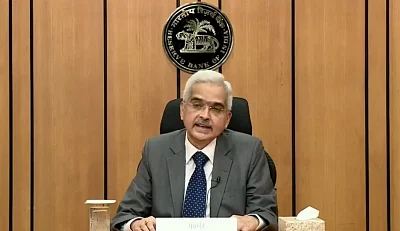
Speaking at the latest Monetary Policy Committee, RBI governor Shaktikanta Das admitted to the current challenges of a clouded outlook caused by the International financial markets and local weather conditions. Retail inflation hit a 5-month high of 7.41% in September, stubbornly above the RBI's upper tolerance limit of 6% while politically-sensitive food inflation was 8.6% — even higher than the 7.62% in August.
This leaves the RBI with no option but to increase interest rates further. Now imagine a situation where middle-class home loan and vehicle loan EMIs go up, even as the poorer sections fret about increasing prices of food items that in turn erode their disposable incomes and thus the demand for industrial goods