NRIs Gain, India Pays: What Will Record FCNR(B) Inflows Cost the Nation?
FCNR(B) deposits, which paid about 3% interest before the scheme was launched, have received 6-6.5% interest.
advertisement
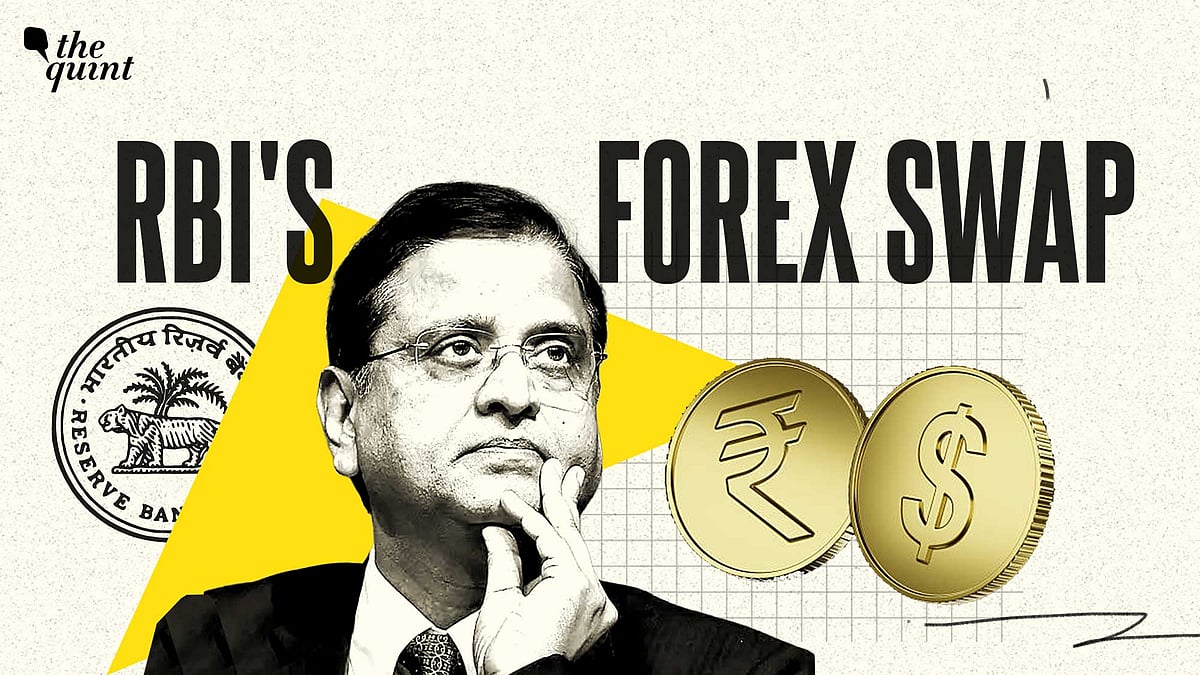
The Reserve Bank of India (RBI) reported provisional forex inflows through Foreign Currency Non-Resident Bank—or FCNR(B)—deposits of $127.23 billion until 31 August 2026. This is when the scheme closed a month earlier than the pre-announced 30 September.
The FCNR(B) inflows are clearly much higher than what the RBI had planned in June. The apex bank is bearing the entire hedging/foreign exchange depreciation cost of FCNR(B) deposits received by Indian banks.
The FCNR(B) inflows are indeed humungous—confirmed by the fact that India’s foreign currency assets (FCAs) climbed to $648.68 billion (and total forex reserves, including gold, to $785.71 billion) on 4 September 2026 against $541.12 billion (total forex reserves $672.59 billion) on 19 June 2026, an increase of more than a hundred billion dollars.
So, what are actual costs of FCNR(B) deposits? Who will bear it—banks, the RBI, government, or the nation? Will it impact the RBI's surplus transfer to the government adversely? And how will the rupee exchange rate behave—favourably or otherwise?
Costs of FCNR(B) Deposits
The FCNR(B) deposits from the NRIs were raised by the banks—public sector, private sector, and foreign banks operating in India.
The RBI decided to absorb all hedging costs for the banks. It took the dollars received in FCNR(B) deposits from banks against rupees and promised to give back equal amount of dollars on deposits' maturity at the same exchange rate—and free them from other associated costs (maintaining zero interest earning cash reserve ratio or capital charge).
FCNR(B) deposits of $127 billion for about 4.5 years (about 50 percent deposits are for five years), will cost roughly $17.5 billion in additional interest cost (at about 3 percent extra interest) or about Rs 1.75 trillion (at Rs 100 per dollar exchange rate) or about Rs 35,000 crore every year in cash. Actual rupee cost of interest would be much higher as the hedging cost of interest paid in dollars is not absorbed by the RBI.
It was expected that the rupee would appreciate as the RBI would get more firepower to defend the rupee. The fact that more than $100 billion came in through the FCNR(B) deposits should have led to rupee appreciating to 90 to a dollar. The experience of the last four months, however, belies this.
The rupee was at 95.79 to a dollar on 4 June 2026.
On 5 June, the day RBI announced the scheme, it strengthened to 94.95 to a dollar.
It has traded in a range-bound manner since then—appreciating to 94.36 on 26 June and 94.49 on 4 September; and depreciating to 96.35 on 16 July, 96.57 on 24 July, and 95.70 pm 21 August.
On 11 September, it traded at 95.56 to a dollar. It did not appreciate at all. On 14 September, it nearly touched 96 to a dollar.
If we consider 5 percent annual depreciation from now on (not an unreasonable bet), the rupee would be close to 120-125 to a dollar in 2030 when the bulk of FCNR(B) deposits mature. If we take additional cost of Rs 25 per dollar of FCNR(B) deposit (over 95 at which these have been received), foreign exchange depreciation cost would be about Rs 3.18 trillion for $127 billion of deposits.
The total bill of additional cost for the FCNR(B) deposits is thus about Rs 5 trillion (Rs 1.75 trillion + Rs 3.18 trillion).
Who Bears the Cost?
The NRI depositors have all gains and no risk.
They will get much higher interest (at least 1.5 percent) over the dollar deposits if kept in the US, Europe, or West Asia. They are earning extra return on their own deposits if they had taken advantage of the leverage (about 15 times) offered by Indian banks (by taking loans at 0.5/1 percent lower interest from their foreign branches). There is no foreign exchange risk for them and no risk of default. It is balle balle for them.
Indian banks cut it very fine and may not really gain anything.
They jumped on the FCNR(B) bandwagon for two reasons:
First, they wanted to please their bosses—the RBI and the government—by making the scheme a grand success.
Second, they had reasoned out that if they could get the FCNR(B) deposits in rupee even at about half a percent lower effective interest cost than their rupee deposit costs, it would benefit them.
In the absence of their ability to lend the FCNR(B) resources at remunerative rates, the liquidity in the banking system has gone through the roof—crossing Rs 10 trillion. The banks cannot invest their extra liquidity in VRR and other facilities offered by the RBI, as they offer lower interest than their cost of FCNR(B) deposits.
They are not putting these resources in government securities either. The banks may eventually lend this money. In the interregnum, however, they suffer a negative carry.
Considering all factors, it seems quite clear that the banks do not bear any part of Rs 5 trillion extra cost bill but their expectations of making any good profits will not materialise: they might end up suffering some cost.
The RBI has strange incentives in the game. It has to deploy the dollars received with the foreign central banks, International Bank of Settlement or invest in foreign governments’ securities. As the RBI keeps its foreign investments and deposits highly liquid, the interest it would earn on its investments is lower than the interest which the banks pay on FCNR(B) deposit. There is thus a net loss of interest on the round-trip of foreign-sourced FCNR(B) deposits ending as the RBI’s deposits with foreigners. As it is not specifically accounted for the RBI, it is the national loss.
An additional Rs 1.75 trillion interest cost/loss is formally on the banks' book and impacts their net interest margin (NIM). However, the banks are putting up a brave face by counting the FCNR(B) flows at 6/6.5 percent as incremental resource, which would increase their profits even if NIMs go down.
Thus, even if the rupee depreciates to 125 to a dollar in 2030, the RBI’s balance sheet would not suffer any loss. Its FCAs would be valued at Rs 125 to a dollar. The loss RBI would generate on giving FCNR(B) dollars at Rs 95 in 2030 would be no loss as its dollar deposits/investments, against would have become equal to Rs 125. In the unlikely situation of the rupee not depreciating in the next four years, the RBI does not bear any cost as there was no depreciation.
Thus, the Rs 3.18 trillion of foreign exchange loss will be suffered by the nation as costlier dollar raises the cost for everyone—importers, oil purchases, debt service and everything else.
Dividend to Government
The FCNR(B)-induced foreign currency reserves increase of about $100 billion, in the absence of any likelihood of strengthening rupee, does not adversely impact the likely dividends to the government from the RBI.
As the nation absorbs the additional cost of Rs 5 trillion while rupee depreciates, the RBI would keep paying good, if not hefty, dividend to the government.
(Subhash Chandra Garg is the Chief Policy Advisor, SUBHANJALI, and Former Finance and Economic Affairs Secretary, Government of India. He's the author of many books, including 'The $10 Trillion Dream Dented, 'We Also Make Policy', and 'Explanation and Commentary on Budget 2025-26'. This is an opinion piece, and the views expressed above are the author’s own. The Quint neither endorses nor is responsible for the same.)
- Access to all paywalled content on site
- Ad-free experience across The Quint
- Early previews of our Special Projects
Published: undefined